Understanding Owners Equity
Understanding owners equity helps business owners see how much of the business belongs to them after accounting for everything the business owns and owes. In simple terms, owners equity represents the remaining value in a business after liabilities are subtracted from assets.
Owners equity changes over time as the business earns profits, experiences losses, receives additional owner investments, or makes distributions to owners. Reviewing equity alongside assets, liabilities, income, and expenses can provide a clearer picture of the business’s overall financial position.
What Is Owners Equity?
Owners equity is the portion of a business’s value that belongs to its owner or owners after all liabilities are deducted from total assets.
The basic accounting relationship is:
Assets – Liabilities = Owners Equity
For example, if a business has $150,000 in total assets and $60,000 in liabilities, the owners equity would generally be:
$150,000 – $60,000 = $90,000
That $90,000 represents the owner’s financial interest in the business based on the amounts recorded in the accounting system.
Owners equity does not necessarily represent the amount of cash the owner could immediately withdraw from the business. Some of the company’s value may be tied up in equipment, inventory, accounts receivable, property, or other assets.
The terminology can also vary depending on the business structure.
A sole proprietorship may use an owner’s equity or owner’s capital account. Partnerships may maintain separate capital accounts for each partner. Corporations generally use stockholders’ or shareholders’ equity accounts.
Although the names differ, the basic concept remains similar: equity represents the owners’ residual interest in the business.
How Is Owners Equity Calculated?
The simplest owners equity calculation starts with the accounting equation:
Owners Equity = Total Assets – Total Liabilities
Step 1: Add the Business Assets
Assets are resources the business owns or controls.
Examples may include:
- Cash
- Business bank accounts
- Accounts receivable
- Inventory
- Equipment
- Vehicles
- Furniture
- Buildings
- Certain prepaid expenses
Suppose a small business has:
- Cash: $35,000
- Accounts receivable: $25,000
- Equipment: $60,000
- Inventory: $20,000
Total assets would equal:
$140,000
Step 2: Add the Business Liabilities
Liabilities represent amounts the business owes.
Examples include:
- Accounts payable
- Business credit card balances
- Loans
- Lines of credit
- Payroll liabilities
- Certain taxes payable
- Other outstanding obligations
Suppose the same business has:
- Accounts payable: $15,000
- Business loan: $35,000
- Credit card balance: $5,000
Total liabilities would equal:
$55,000
Step 3: Subtract Liabilities From Assets
The owners equity would therefore be:
$140,000 – $55,000 = $85,000
The calculation itself is straightforward. The more difficult part is making sure the asset and liability balances are accurate.
If receivables are overstated, loans are missing, transactions have not been recorded, or bank accounts are unreconciled, the resulting equity figure may also be inaccurate.
What Increases Owners Equity?
Several types of transactions can increase owners equity.
Business Profits
Profits are one of the primary ways equity grows.
When business revenue exceeds expenses, the resulting net income generally increases equity.
For example, if a business starts the year with $80,000 in equity and earns $25,000 in net income, equity may increase, assuming there are no other changes such as owner withdrawals.
Owner Contributions
When an owner contributes additional money or property to the business, the owner’s capital or equity can increase.
Examples might include:
- Depositing personal funds into the business
- Contributing equipment
- Contributing other assets
Proper bookkeeping is important because owner contributions should generally be distinguished from business revenue.
An owner putting $10,000 of personal money into the business is different from the business earning $10,000 from customers.
Retained Earnings
In corporations, profits that remain in the company rather than being distributed to shareholders may contribute to retained earnings, which is part of shareholders’ equity.
Over time, consistently retaining earnings can strengthen the equity position of a business.
What Decreases Owners Equity?
Owners equity can also decline.
Business Losses
When expenses exceed revenue, the business experiences a net loss.
Losses generally reduce owners equity.
If a business begins the year with $60,000 in equity and records a $15,000 loss, equity may decline accordingly, depending on other transactions during the period.
Owner Withdrawals
Money taken out of a sole proprietorship by the owner is often recorded through an owner’s draw account.
Draws reduce the owner’s equity in the business.
For example, if an owner withdraws $20,000 for personal use, the withdrawal generally reduces equity rather than being treated as an ordinary business operating expense.
Distributions
Partnerships, LLCs, and corporations may make distributions to owners or shareholders.
Depending on the entity structure and accounting treatment, these distributions can reduce equity accounts.
Declining Asset Values
Certain accounting adjustments may reduce the recorded value of assets.
For example, depreciation reduces the book value of some long-term assets over time. Asset write-downs may also affect the financial statements.
These accounting changes can ultimately affect equity through their impact on income or asset balances.
Increasing Liabilities Without Corresponding Asset Growth
Borrowing money does not necessarily reduce equity immediately because receiving loan proceeds generally increases both cash and liabilities.
However, growing liabilities combined with falling assets, losses, or heavy spending can contribute to a weaker equity position over time.
Owners Equity Examples for Small Businesses
Looking at practical examples can make owners equity easier to understand.
Example 1: Sole Proprietor
A landscaping business has:
- Assets: $90,000
- Liabilities: $25,000
Owners equity is:
$90,000 – $25,000 = $65,000
If the business later earns another $15,000 in profit and the owner does not withdraw additional funds, equity may increase.
Example 2: Owner Adds Money to the Business
A consulting business has $40,000 in equity.
The owner contributes an additional $10,000 of personal funds to support expansion.
Ignoring other transactions, the contribution may increase owners equity to approximately:
$50,000
The contribution should be recorded as an owner investment rather than business income.
Example 3: Business Loss and Owner Draw
A small contractor begins the year with $75,000 in equity.
During the year:
- The business records a $12,000 loss.
- The owner withdraws $8,000.
Ignoring other equity transactions, equity could decrease to:
$55,000
This example shows how both operating performance and owner withdrawals can affect the equity balance.
Example 4: Growing Business
A business begins with:
- $200,000 in assets
- $120,000 in liabilities
Initial equity:
$80,000
At year-end, the business has:
- $260,000 in assets
- $140,000 in liabilities
Ending equity:
$120,000
The increase may reflect profits, additional owner contributions, or other accounting changes.
Looking at the underlying transactions is necessary to understand why equity increased.
Owners Equity vs Business Assets and Liabilities
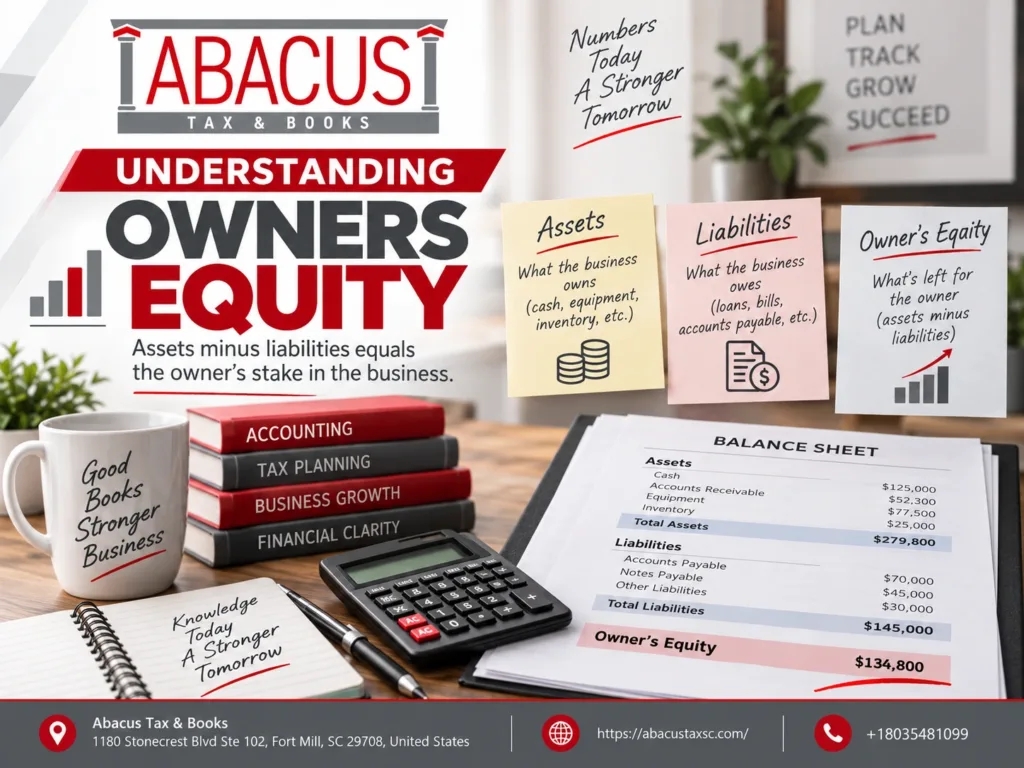
Assets, liabilities, and equity are closely connected but represent different things.
Assets
Assets represent resources owned or controlled by the business.
Examples include:
- Cash
- Inventory
- Equipment
- Customer receivables
- Vehicles
- Property
Liabilities
Liabilities represent what the business owes to others.
Examples include:
- Vendor bills
- Loans
- Credit card balances
- Payroll obligations
- Other debts
Owners Equity
Owners equity represents the remaining interest after subtracting liabilities from assets.
The complete accounting equation is:
Assets = Liabilities + Owners Equity
Suppose a business has $100,000 in assets.
If $35,000 of those assets are effectively financed through liabilities, the remaining $65,000 represents equity.
This relationship must stay balanced within a properly maintained accounting system.
Where Does Owners Equity Appear on Financial Statements?
Owners equity primarily appears on the balance sheet.
The balance sheet presents the financial position of a business at a specific point in time.
It generally includes three main sections:
- Assets
- Liabilities
- Equity
A simplified balance sheet might look like this:
Assets
Cash: $40,000
Accounts receivable: $25,000
Equipment: $55,000
Total Assets: $120,000
Liabilities
Accounts payable: $15,000
Business loan: $30,000
Total Liabilities: $45,000
Owners Equity: $75,000
The accounting equation remains balanced:
$120,000 = $45,000 + $75,000
Equity is also affected indirectly by the income statement.
The income statement reports revenue, expenses, and profit or loss over a period of time.
Net income can increase equity, while net losses can reduce it.
Depending on the business structure, additional financial reports may also show changes in owner’s capital, retained earnings, contributions, distributions, or other equity accounts.
Why Owners Equity Matters to Business Owners
Owners equity provides another way to evaluate the financial position of a business.
It should not be viewed in isolation, but it can reveal useful trends.
It Shows the Net Book Value of the Business
Subtracting liabilities from assets shows the owner’s residual financial interest based on the accounting records.
It Helps Track Changes Over Time
Comparing equity from one year to the next can show whether the company’s financial position is strengthening or weakening.
If equity consistently increases because of profitable operations, that may indicate that the company is retaining value.
If equity continually decreases, owners may need to understand whether losses, withdrawals, growing liabilities, or another factor is responsible.
It Helps Put Debt in Context
A business with $500,000 in assets and $100,000 in liabilities looks different from a business with $500,000 in assets and $475,000 in liabilities.
Both have the same asset level, but their equity positions are very different.
It Supports Better Financial Review
Equity provides context when reviewing:
- Profitability
- Debt
- Asset levels
- Owner withdrawals
- Owner investments
- Business growth
Business owners can use this information alongside other accounting reports to better understand how the company’s financial position is changing.
Common Owners Equity Mistakes
Owners equity can become confusing when transactions are categorized incorrectly.
Recording Owner Contributions as Revenue
Money contributed personally by the owner generally should not automatically be treated as sales or operating revenue.
Misclassifying contributions can distort income reports.
Recording Owner Draws as Business Expenses
Owner withdrawals are generally equity transactions rather than ordinary operating expenses.
Incorrectly recording them as expenses can make business profitability appear lower than it actually is.
Mixing Personal and Business Transactions
When personal spending runs through business accounts, it becomes harder to determine what represents legitimate business activity versus owner-related transactions.
Forgetting Existing Liabilities
Missing loans, credit card balances, unpaid bills, or other obligations can overstate owners equity.
Failing to Reconcile Accounts
If bank and credit card accounts are not reconciled, asset and liability balances may be wrong.
That means the equity calculation can also be wrong.
Assuming Equity Equals Available Cash
A business might have $200,000 in equity but only $15,000 in its bank account.
The rest of the equity may be represented by inventory, equipment, receivables, or other assets.
Equity should not be confused with cash available for spending or withdrawal.
Ignoring Negative Equity
Negative equity occurs when liabilities exceed assets.
For example:
Assets: $80,000
Liabilities: $105,000
Owners equity would be:
-$25,000
Negative equity does not automatically explain why a business is in that position. Owners should review the underlying financial records to understand whether losses, debt, distributions, asset reductions, or other factors contributed to the result.
How Accurate Accounting Helps Track Owners Equity
Owners equity is only as reliable as the accounting records behind it.
If transactions are missing or incorrectly categorized, the equity section of the balance sheet may not reflect the business accurately.
Consistent bookkeeping helps ensure that:
- Owner contributions are recorded correctly
- Owner draws and distributions are separated from expenses
- Revenue and expenses are categorized properly
- Loan balances are updated
- Bank and credit card accounts are reconciled
- Asset purchases are recorded
- Accounts receivable and payable remain current
- Financial reports stay consistent
At Abacus Tax & Books, we help small business owners maintain organized accounting records that provide a clearer view of assets, liabilities, income, expenses, and equity.
Accurate books make it easier to understand why owners equity changes from one period to another.
For example, if equity decreased during the year, good records can help determine whether the decline resulted from operating losses, owner withdrawals, asset adjustments, or another factor.
Similarly, when equity increases, accounting reports can show whether the change came from stronger profitability, additional owner investment, or other activity.
Owners equity should therefore be viewed as part of the broader financial picture rather than as a standalone measurement of business success.
FAQs
What does owners equity mean in simple terms?
Owners equity represents the value remaining in a business after its liabilities are subtracted from its assets. It reflects the owner’s financial interest in the company according to the accounting records.
What is the formula for owners equity?
The basic formula is:
Owners Equity = Assets – Liabilities
If a business has $120,000 in assets and $50,000 in liabilities, owners equity would generally be $70,000.
Is owners equity the same as cash?
No. Equity may include value tied up in cash, equipment, inventory, receivables, property, and other assets. A business can have significant equity without having the same amount available in its bank account.
Can owners equity be negative?
Yes. Negative equity occurs when total liabilities exceed total assets. Owners should review their financial statements and accounting records to understand what caused the negative balance.
Does profit increase owners equity?
Generally, yes. Net income typically increases equity, while a net loss reduces it, assuming other factors remain unchanged.
Do owner withdrawals reduce equity?
Generally, yes. Owner draws or certain distributions reduce the owner’s equity because value is being removed from the business for the owner’s benefit.
Is owners equity the same for every business structure?
The underlying concept is similar, but terminology and accounting presentation can differ. Sole proprietorships may use owner’s capital accounts, partnerships may track individual partner capital, and corporations typically report shareholders’ equity and retained earnings.
Where can I find owners equity on my financial statements?
Owners equity is generally shown on the balance sheet below the business’s liabilities. The exact labels may vary depending on the business structure and accounting system.
Why does my owners equity change every month?
Equity may change because of profits, losses, owner contributions, withdrawals, distributions, and certain accounting adjustments. Reviewing the balance sheet and income statement together can help explain the change.
How does bookkeeping help track owners equity?
Accurate bookkeeping keeps asset, liability, income, expense, contribution, and withdrawal accounts current. This allows the equity section of the balance sheet to provide a more reliable picture of the owner’s financial interest in the business.