Accounting Terms Every Business Owner Should Know
Understanding financial reports becomes easier when business owners recognize the language used in accounting. From revenue and expenses to assets and cash flow, knowing accounting terms every business owner should know helps explain how money moves through a company and what financial statements reveal about its performance.
Small business owners do not need to become accountants to understand their financial information. Learning a few essential definitions, along with practical examples, can make everyday business decisions clearer and conversations with accounting professionals more productive.
Quick Answer: Which Accounting Terms Should Business Owners Know?
The most important accounting terms for small business owners describe how a company earns money, spends money, owns assets, and meets financial obligations.
Understanding these terms makes it easier to review financial statements, evaluate profitability, and recognize potential financial problems.
Here are some essential accounting terms:
- Revenue: Money earned from selling products or providing services.
- Expenses: Costs recognized in operating and maintaining a business.
- Cost of goods sold (COGS): Direct costs associated with products or services sold.
- Assets: Resources the business owns or controls that provide economic value.
- Liabilities: Financial obligations the business owes.
- Equity: The remaining ownership interest after subtracting liabilities from assets.
- Accounts receivable: Money customers owe the business.
- Accounts payable: Money the business owes suppliers or vendors.
- Gross profit: Revenue remaining after subtracting cost of goods sold.
- Net profit: Earnings remaining after accounting for applicable expenses and other income or losses.
- Cash flow: Money moving into and out of the business.
- Depreciation: Allocation of certain tangible asset costs over their useful lives.
- Amortization: Allocation of certain intangible asset costs over time.
These definitions provide a foundation for understanding financial reports.
However, accounting terminology can have more specific meanings depending on the reporting method, business structure, and tax requirements.
Revenue, Income, and Sales
Revenue, income, and sales are frequently used in conversations about business finances.
Although they are related, they do not always mean the same thing.
What is revenue?
Revenue is the amount a business earns from its normal operations before subtracting expenses.
For example, a landscaping company that earns $15,000 from customer services during a month generates $15,000 in service revenue.
Revenue helps measure the amount of business activity during a reporting period.
It does not indicate how much money the company keeps after paying its expenses.
What are sales?
Sales generally refers to the value of products or services sold to customers.
For many small businesses, sales and operating revenue are closely related.
For example, a retail store may report $25,000 in sales revenue for the month.
However, gross sales and net sales may differ.
Net sales generally reflect sales after applicable returns, allowances, and discounts.
What does income mean?
The word income can have different meanings depending on the context.
In everyday accounting conversations, business owners may use income to describe money earned from operations.
However, financial reports often use terms such as net income to describe profit after expenses.
For example, a business might generate $25,000 in revenue but report $6,000 in net income.
Understanding which meaning is being used helps prevent confusion when reviewing financial reports.
Expenses and Cost of Goods Sold
Expenses and cost of goods sold both affect profitability, but they describe different types of business costs.
What are business expenses?
Expenses are costs recognized in connection with operating a business and earning revenue.
Common examples include:
- Office rent.
- Utilities and internet services.
- Advertising and marketing.
- Insurance.
- Administrative salaries.
- Professional services.
- Certain repairs and maintenance.
For example, a dental office might pay $2,000 in monthly rent and $300 for internet and communication services.
These costs support business operations.
However, not every payment is immediately recorded as an expense. Equipment purchases, loan principal payments, and certain prepaid costs may receive different accounting treatment.
What is cost of goods sold?
Cost of goods sold (COGS) represents the direct costs associated with the goods sold during a period.
For a retailer, COGS may include the purchase cost of merchandise sold.
For a manufacturer, it may include direct materials, direct labor, and applicable production overhead.
For example, a store sells a piece of furniture for $900.
If the furniture cost the store $550, the transaction generates $350 in gross profit before considering other expenses.
Some service businesses track comparable direct service costs under cost of services rather than traditional COGS.
The classification depends on the company’s activities and accounting practices.
Why the difference matters
Separating direct costs from operating expenses helps business owners understand how much profit remains after delivering their products or services.
It also makes financial comparisons more useful.
A business may increase sales while experiencing higher direct costs that reduce its gross profit.
Assets, Liabilities, and Equity
Assets, liabilities, and equity describe a company’s financial position.
These terms form the foundation of the balance sheet.
What are assets?
Assets are resources the business owns or controls that provide economic benefits.
Common examples include cash, accounts receivable, inventory, equipment, vehicles, and buildings.
For example, a plumbing company may have $20,000 in cash, $8,000 in outstanding customer invoices, and $35,000 in equipment.
These resources are part of its assets.
What are liabilities?
Liabilities are obligations the business owes to other parties.
Examples include business loans, outstanding supplier bills, credit card balances, and certain taxes payable.
A company may own valuable equipment while still owing money on the financing used to purchase it.
What is equity?
Equity represents the owners’ residual interest in the business after accounting for liabilities.
The basic accounting equation is:
Assets = Liabilities + Equity
Consider a business with the following balances:
| Financial item | Amount |
| Total assets | $80,000 |
| Total liabilities | $30,000 |
| Total equity | $50,000 |
In this example, the business has $50,000 in book equity.
However, book equity does not necessarily represent how much the business could sell for in the market.
Understanding these categories helps owners evaluate financial obligations and the resources available to meet them.
Accounts Receivable and Accounts Payable
Accounts receivable and accounts payable describe money expected from customers and money owed to vendors.
They are especially important for businesses that buy or sell on credit.
What is accounts receivable?
Accounts receivable (AR) is money customers owe a business for products or services already provided on credit.
For example, a contractor completes a $4,000 project and sends an invoice with payment due in 30 days.
Under accrual accounting, the company generally records $4,000 in accounts receivable when the revenue is earned and the payment is owed.
When the customer pays, the receivable is reduced and cash increases.
What is accounts payable?
Accounts payable (AP) is money a business owes suppliers for goods or services received on credit.
For example, a restaurant receives $1,200 in supplies with payment due the following month.
Under accrual accounting, the restaurant generally records the amount as accounts payable until payment is made.
Why these terms matter
Accounts receivable helps business owners monitor outstanding customer payments.
Accounts payable helps them understand upcoming vendor obligations.
A business can have strong sales while experiencing cash shortages if customers pay slowly and supplier payments are due sooner.
Reviewing both balances supports better payment planning.
Gross Profit vs. Net Profit
Gross profit and net profit measure different stages of business profitability.
Understanding the difference helps owners determine whether financial problems are related to direct costs or broader operating expenses.
What is gross profit?
Gross profit is the amount remaining after subtracting cost of goods sold from net revenue.
The basic formula is:
Gross Profit = Net Revenue − Cost of Goods Sold
For example, a retail business generates $20,000 in net sales and has $8,000 in cost of goods sold.
Its gross profit is $12,000.
This amount must still cover operating expenses and other applicable costs.
What is net profit?
Net profit, also called net income, is the amount remaining after accounting for the business’s expenses and other relevant income or losses.
Using the same example:
| Financial item | Amount |
| Net sales revenue | $20,000 |
| Cost of goods sold | ($8,000) |
| Gross profit | $12,000 |
| Operating expenses | ($7,000) |
| Interest and income tax expenses | ($1,000) |
| Net profit | $4,000 |
The business generated $20,000 in sales but earned $4,000 in net profit.
The distinction matters because higher sales do not automatically produce higher profits.
If expenses increase faster than revenue, profitability may decline even when customer demand is strong.
Cash Flow vs. Profit
Cash flow and profit are closely connected, but they are not interchangeable.
A business can report a profit while having limited cash available to pay its bills.
What is cash flow?
Cash flow refers to money entering and leaving a business.
Cash inflows may include customer payments, loan proceeds, and owner contributions.
Cash outflows may include supplier payments, payroll, equipment purchases, and loan repayments.
These movements help determine how much money is available at a particular time.
How is profit different?
Profit measures earnings after applicable expenses are recognized under the company’s accounting method.
Under accrual accounting, revenue may be recorded before the customer pays.
For example, a business completes $10,000 in services and recognizes the revenue, but its customers have not yet paid.
The company may report a profit while still waiting to collect the cash.
Why should owners monitor both?
Profitability helps determine whether the business generates sufficient earnings relative to its expenses.
Cash flow helps determine whether money is available to meet financial obligations.
A profitable business can still struggle if customer payments are delayed or significant purchases require cash.
Monitoring both provides a more complete understanding of financial health.
Accrual vs. Cash-Basis Accounting
Cash-basis and accrual accounting are two common methods for determining when income and expenses are recognized.
The method a business uses affects how transactions appear in its accounting records and financial reports.
What is cash-basis accounting?
Under the cash method, businesses generally recognize income when payment is received and expenses when they are paid, subject to applicable accounting and tax rules.
For example, a business provides a $2,000 service in March but receives payment in April.
Under a straightforward cash-basis example, it records the income in April.
This approach can make it easier to relate recorded income and expenses to cash activity.
However, certain businesses and transactions are subject to special accounting rules.
What is accrual accounting?
Under the accrual method, businesses generally recognize revenue when earned and expenses when incurred, regardless of when the related cash changes hands.
Using the same example, the business records $2,000 in revenue in March, even though the customer pays in April.
Accounts receivable records the outstanding amount until payment arrives.
Which accounting method is better?
Neither method is automatically right for every small business.
Cash-basis accounting can be simpler for eligible businesses with straightforward transactions.
Accrual accounting can provide a more complete picture of earned revenue, outstanding bills, and financial obligations.
However, eligibility, tax requirements, inventory rules, and the nature of business operations can influence which accounting method is appropriate.
Business owners should consult a qualified accounting or tax professional before choosing or changing their accounting method.
Depreciation and Amortization
Depreciation and amortization explain how certain asset costs are allocated over time rather than recognized entirely as an immediate expense.
Both concepts are important when businesses purchase assets that provide benefits over several years.
What is depreciation?
Depreciation generally refers to allocating the cost of a tangible long-term asset over its estimated useful life.
Tangible assets include equipment, machinery, vehicles, and certain buildings.
For example, a business purchases equipment for $12,000.
If the equipment has an estimated four-year useful life and no residual value, straight-line depreciation for financial reporting could be $3,000 annually.
The actual treatment depends on applicable accounting policies and the asset’s characteristics.
What is amortization?
Amortization generally refers to allocating the cost of certain intangible assets over their useful lives.
Examples may include eligible patents, licenses, or acquired intellectual property.
For example, a business purchases an eligible intangible asset for $10,000 and determines that it should be amortized evenly over five years.
The annual amortization expense would be $2,000.
Not all intangible assets are amortized under financial reporting rules.
How are these different from tax deductions?
Financial accounting depreciation and amortization may differ from the amounts or timing allowed for tax purposes.
Certain assets may qualify for accelerated deductions, while other purchases may need different treatment.
Business owners should not assume the accounting expense recorded in their books automatically equals the tax deduction available on their returns.
What Is a Balance Sheet?
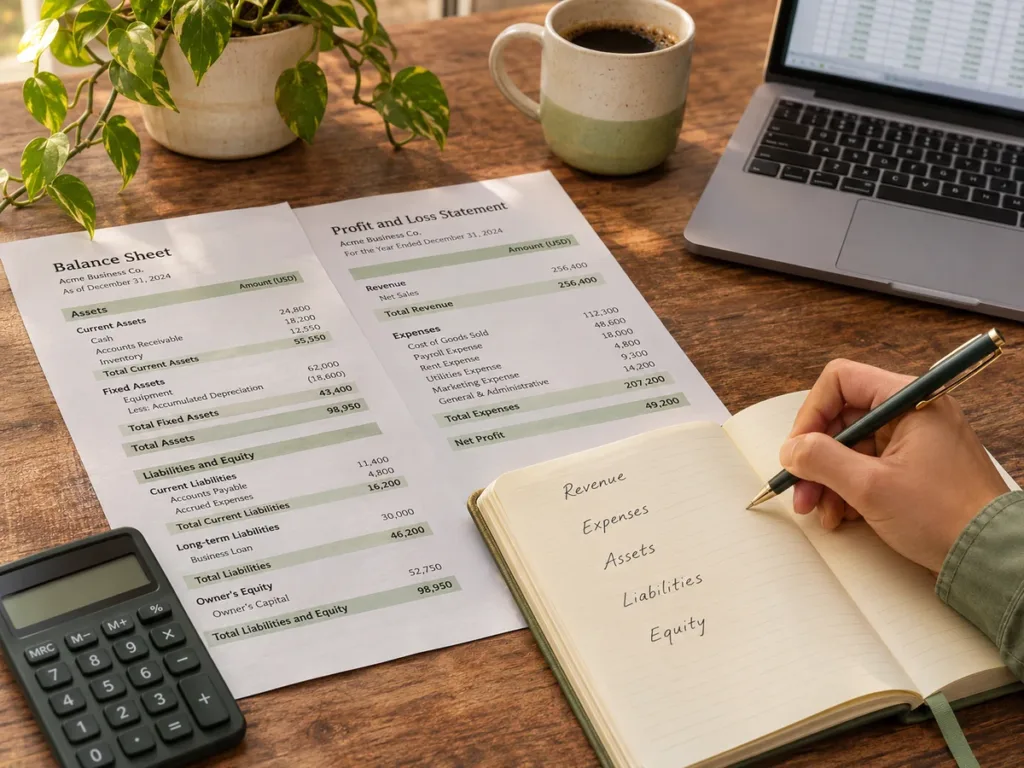
A balance sheet is a financial statement showing a business’s assets, liabilities, and equity at a specific point in time.
It provides a snapshot of what the business owns, what it owes, and the remaining ownership interest.
What information appears on a balance sheet?
A balance sheet generally contains three main sections.
Assets include cash, outstanding customer balances, inventory, and qualifying long-term resources.
Liabilities include outstanding bills, loans, and other financial obligations.
Equity represents the remaining interest after liabilities are deducted from assets.
Example of a simple balance sheet
| Category | Amount |
| Cash and other assets | $60,000 |
| Total assets | $60,000 |
| Total liabilities | $25,000 |
| Total equity | $35,000 |
| Liabilities + equity | $60,000 |
The two sides of the accounting equation are equal.
Why is a balance sheet useful?
Business owners can use balance sheets to evaluate outstanding obligations, changes in asset balances, and their financial position over time.
For example, a company might have significant assets but also carry substantial debt.
Reviewing the balance sheet can help the owner understand that relationship.
However, a balance sheet does not provide a complete picture of profitability or cash movement during the reporting period.
Other financial statements are needed for that information.
What Is an Income Statement?
An income statement, also called a profit and loss statement or P&L, shows a business’s revenue, expenses, and profit or loss over a specific period.
Unlike a balance sheet, which reflects a particular date, an income statement covers a period such as a month, quarter, or year.
What appears on an income statement?
A typical income statement may include revenue, cost of goods sold, gross profit, operating expenses, and net income.
For example, a business might generate $50,000 in revenue during a quarter and recognize $42,000 in total expenses.
Assuming no other income, losses, or adjustments, it would report $8,000 in net profit.
Why should business owners review income statements?
Income statements help owners identify trends in sales, expenses, and profitability.
A company might discover that revenue increased but net profit declined because operating costs rose.
This information can help guide decisions about pricing, purchasing, staffing, and spending.
How is an income statement different from a balance sheet?
The income statement explains financial performance over time.
The balance sheet shows financial position on a particular date.
Both statements provide useful information, but neither should be reviewed in isolation.
Business owners can gain a clearer understanding of their finances by comparing income statements, balance sheets, and cash flow information.
Accounting Support in Fort Mill
Understanding financial terminology is an important starting point, but applying accounting concepts to everyday business decisions can still be challenging.
At Abacus Tax & Books, we help small business owners understand their financial information and maintain organized accounting records.
Whether a business is reviewing revenue and expenses, examining outstanding customer balances, or trying to understand financial statements, having reliable records makes those conversations more productive.
Our team provides bookkeeping, accounting, tax consulting, and QuickBooks support for small and medium-sized businesses.
We work with business owners in Fort Mill, Tega Cay, Rock Hill, and surrounding communities who want clearer financial information and a better understanding of their accounting responsibilities.
Financial reports should provide useful information rather than create confusion.
By helping businesses maintain organized records and understand important accounting concepts, we support more informed financial decision-making.
Make Your Business Numbers Easier to Understand With Abacus Tax & Books
Accounting terminology should not prevent business owners from understanding how their companies are performing.
Knowing the difference between revenue and profit, recognizing outstanding liabilities, and understanding financial statements can make everyday financial decisions easier.
At Abacus Tax & Books, we help small business owners address bookkeeping concerns, review financial information, and understand the records used to manage their operations.
Our accounting and QuickBooks support services are designed to help businesses maintain organized financial information and identify areas that may require attention.
We also offer tax preparation and consulting services for businesses seeking support with their tax-related responsibilities.
Whether you are starting a business or trying to better understand an existing company’s finances, our team is available to discuss your accounting needs.
Contact Abacus Tax & Books at (803) 548-1099 to schedule a consultation and learn how we can help you better understand your business finances.
FAQs About Common Accounting Terms
What are the most important accounting terms for beginners?
Revenue, expenses, assets, liabilities, equity, accounts receivable, accounts payable, gross profit, net profit, and cash flow are important starting points. These terms help explain common financial transactions and reports.
What is the difference between revenue and profit?
Revenue is the amount earned from business sales or services before expenses. Profit is the amount remaining after applicable costs and expenses are deducted.
What does equity mean in small business accounting?
Equity represents the owners’ remaining interest in the business after subtracting liabilities from assets. It reflects book value rather than necessarily indicating the company’s market value.
Is cash flow the same as net income?
No. Cash flow measures money entering and leaving the business, while net income measures profit according to the accounting method used. A business can report income without receiving the related cash immediately.
What is the difference between accounts payable and accounts receivable?
Accounts payable represents money a business owes suppliers or vendors. Accounts receivable represents money customers owe the business for sales made on credit.
Why should business owners understand accounting terms?
Understanding accounting terminology helps business owners read financial statements, recognize potential problems, communicate with accounting professionals, and make more informed decisions about their operations.