Managing Seasonal Cash Flow: How Small Businesses Can Prepare for Slower Months
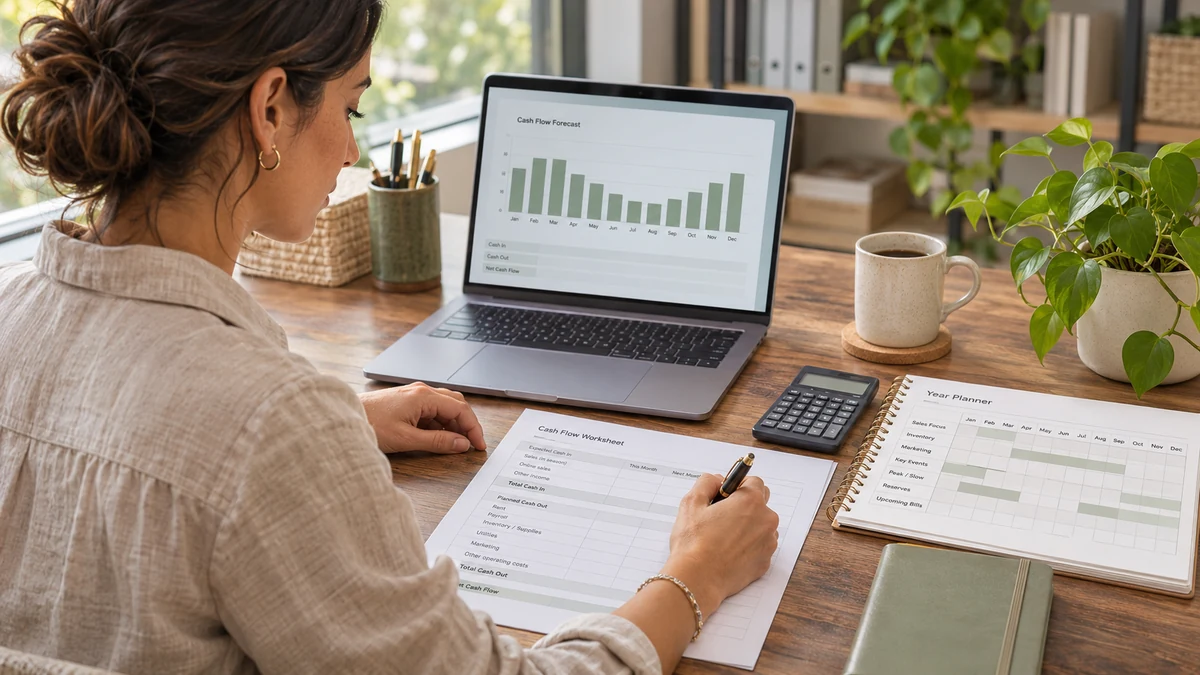
Managing seasonal cash flow helps small businesses prepare for changes in revenue throughout the year. When sales increase during busy months and decline during slower periods, business owners must plan carefully to cover payroll, rent, inventory, and other operating expenses. A profitable season does not always guarantee enough cash for the months that follow.
Understanding seasonal revenue patterns, forecasting upcoming expenses, and building appropriate financial reserves can help businesses maintain stability. With organized records and a practical cash flow plan, owners can make better financial decisions throughout the year.
Quick Answer: How Do You Manage Seasonal Cash Flow?
Small businesses can manage seasonal cash flow by forecasting expected income, monitoring expenses, building cash reserves during profitable months, and planning ahead for periods when revenue typically declines.
The goal is to ensure that enough money is available to cover financial obligations regardless of seasonal changes in sales.
Practical strategies include:
- Review historical revenue: Identify which months consistently generate higher or lower sales.
- Create cash flow forecasts: Estimate when money will enter and leave the business.
- Build financial reserves: Set aside funds during stronger months to support slower periods.
- Plan major expenses: Schedule flexible purchases around expected cash availability.
- Monitor accounts receivable: Follow up on unpaid invoices before cash shortages develop.
- Adjust seasonal operations: Review staffing, purchasing, and inventory needs based on expected demand.
- Review financial records: Use current bookkeeping information to monitor cash balances and identify potential problems.
These steps are particularly useful for businesses with predictable changes in customer demand.
However, seasonal planning should reflect each company’s operating expenses, payment schedules, and financial responsibilities.
A business with high fixed costs may require a different approach than one that can reduce expenses significantly during slower months.
Why Seasonal Businesses Face Cash Flow Challenges
Seasonal businesses generate different amounts of revenue throughout the year.
Some experience predictable increases in customer activity during holidays, summer months, or particular weather conditions.
Others depend on industries where demand changes according to construction schedules, tourism, or consumer spending patterns.
The challenge is that business expenses do not always decline when sales decrease.
Fixed expenses continue during slower months
A landscaping company may generate substantial revenue during its busiest service months.
However, during the winter, it may still need to cover equipment payments, insurance, storage, and other operating costs.
Similarly, a retail business might experience strong holiday sales but continue paying rent, utilities, and software subscriptions during quieter months.
These ongoing expenses can place pressure on available cash.
Revenue and payments do not always arrive together
A business may complete significant work during its busiest season but receive payment several weeks later.
For example, a contractor might finish a project in June but not receive the final customer payment until July or August.
Although the revenue may already appear in financial reports, the actual cash is not available until payment arrives.
This difference between revenue recognition and cash collection is important for seasonal planning.
Seasonal preparation requires spending in advance
Many businesses must purchase supplies, hire employees, or prepare equipment before their busiest periods begin.
A retail store may need to purchase holiday inventory months before customers make those purchases.
A lawn care company may need to maintain equipment and hire seasonal workers before demand increases.
These upfront costs can create temporary cash shortages even when the upcoming season is expected to be profitable.
Understanding these patterns is the foundation of effective seasonal cash management.
How to Identify Your Busy and Slow Seasons
Before developing a seasonal cash flow plan, business owners need to understand how revenue and expenses change throughout the year.
Historical accounting information can reveal patterns that may not be obvious from day-to-day operations.
Review previous financial records
Start by examining monthly revenue for the previous two or three years, if reliable records are available.
Look for recurring increases and decreases in sales.
For example, a business might discover that revenue consistently rises between April and September before declining during the winter.
Another company might experience its highest sales in November and December.
These patterns can help identify when additional cash is likely to become available.
Compare expenses with seasonal revenue
Revenue alone does not tell the complete story.
A business may generate more sales during a busy season while also spending more on labor, supplies, transportation, and inventory.
Review monthly expenses alongside revenue to determine how much cash is typically needed to support those sales.
A busy month with high operating costs may contribute less available cash than expected.
Consider outside factors
Historical patterns provide useful information, but they should not be treated as guarantees.
Seasonal demand can change because of:
- Weather conditions and severe storms.
- Changes in customer spending.
- Local events and tourism activity.
- Construction and project schedules.
- Supplier price increases.
- Changes in competition.
- Economic conditions affecting customers.
Businesses should combine historical trends with current information when estimating future activity.
Identify the timing of cash shortages
A slow sales month is not always the month when cash becomes most limited.
For example, a retailer might generate strong December sales but face significant supplier payments in January.
Reviewing the timing of receipts and payments helps identify when the business is most financially vulnerable.
How Cash Flow Forecasting Helps You Plan Ahead
Cash flow forecasting involves estimating how much money a business expects to receive and pay during a future period.
Unlike a sales forecast, which focuses on expected revenue, a cash flow forecast considers when payments will actually occur.
This distinction matters for seasonal businesses.
Start with the current cash balance
The forecast should begin with the amount of available business cash.
Next, estimate expected incoming payments.
These might include customer payments, deposits, subscription revenue, or other anticipated receipts.
Then subtract expected outgoing payments, such as payroll, rent, insurance, loan payments, inventory purchases, and taxes.
A simple example illustrates the process.
| Cash flow item | Illustrative amount |
| Beginning cash balance | $25,000 |
| Expected customer collections | $18,000 |
| Expected operating payments | ($30,000) |
| Projected ending cash balance | $13,000 |
This example shows that the business expects to finish the period with $13,000 in cash.
However, the owner must also consider whether payments are due before customer funds arrive.
A monthly forecast may show a positive ending balance even if cash becomes insufficient partway through the month.
Use monthly and short-term forecasts
Monthly forecasts can help identify broad seasonal patterns.
For businesses facing immediate payment timing challenges, a rolling weekly forecast covering the next several weeks can provide additional detail.
For example, a 13-week forecast can help identify when payroll, supplier payments, and customer collections are expected to occur.
Update forecasts regularly
Forecasts should change as new information becomes available.
If customers delay payments or sales fall below expectations, the business should revise its projected cash balance.
Similarly, unexpected expenses or stronger sales may affect future cash availability.
Managing seasonal cash flow becomes more effective when forecasting is an ongoing process rather than an annual exercise.
How to Build Cash Reserves Before Slower Months
Cash reserves provide funds that businesses can use when operating revenue declines or unexpected expenses occur.
For seasonal companies, reserves are particularly important because slower months may be predictable.
However, there is no universal reserve amount that works for every business.
Calculate expenses that continue year-round
Start by identifying essential costs that must be paid even when revenue is limited.
These may include:
- Rent or mortgage payments.
- Insurance premiums.
- Essential payroll expenses.
- Utilities and communication services.
- Equipment financing.
- Loan payments.
- Required software subscriptions.
- Taxes and other scheduled obligations.
Next, estimate how much incoming cash will be available during the slower season.
The difference between expected receipts and required payments helps establish the amount of cash the business may need.
Set aside money during stronger months
Rather than treating every profitable month as an opportunity for additional spending, owners can designate part of available cash for future seasonal expenses.
A separate business savings account may help keep operating reserves visible.
The appropriate savings amount should reflect projected cash shortages, financial obligations, and the business’s risk exposure.
Prepare for unexpected costs
Seasonal plans should also consider unexpected events.
Equipment breakdowns, emergency repairs, customer cancellations, and delayed payments can affect cash availability.
A reserve that only covers the exact amount of projected expenses may not provide enough flexibility.
Businesses should evaluate possible financial risks when determining how much cash to maintain.
Avoid confusing profit with available cash
A business may report a profitable month while having limited cash because customers have not paid outstanding invoices.
Before transferring money into reserves or making additional purchases, owners should review actual cash balances and upcoming obligations.
This helps prevent a profitable-looking month from creating a cash shortage later.
How to Time Expenses Around Seasonal Revenue
Timing certain business expenses can help reduce financial pressure during slower months.
However, not every cost can or should be postponed.
The goal is to distinguish between necessary obligations and purchases that offer some scheduling flexibility.
Separate fixed and flexible expenses
Fixed expenses generally continue regardless of sales volume.
Examples include rent, insurance, and certain financing obligations.
Flexible expenses may change according to business activity.
These can include advertising campaigns, optional equipment purchases, discretionary travel, and some supply orders.
Reviewing these categories helps identify which costs might be adjusted when revenue declines.
Schedule major purchases carefully
Consider a business planning to replace office equipment.
If the existing equipment remains functional, the owner might schedule the purchase after a stronger sales period rather than immediately before the slow season.
However, postponing essential repairs could create additional expenses or interrupt operations.
Business owners should consider both financial timing and operational needs.
Review supplier payment terms
Some suppliers offer payment terms that allow businesses to purchase goods before payment is due.
These arrangements may help align expenses with expected customer collections.
However, businesses should understand due dates, discounts, interest, and late-payment consequences.
Delaying payments beyond agreed terms is not a sustainable cash management strategy.
Plan taxes and annual payments
Property taxes, income tax payments, insurance renewals, and other periodic obligations can create significant cash requirements.
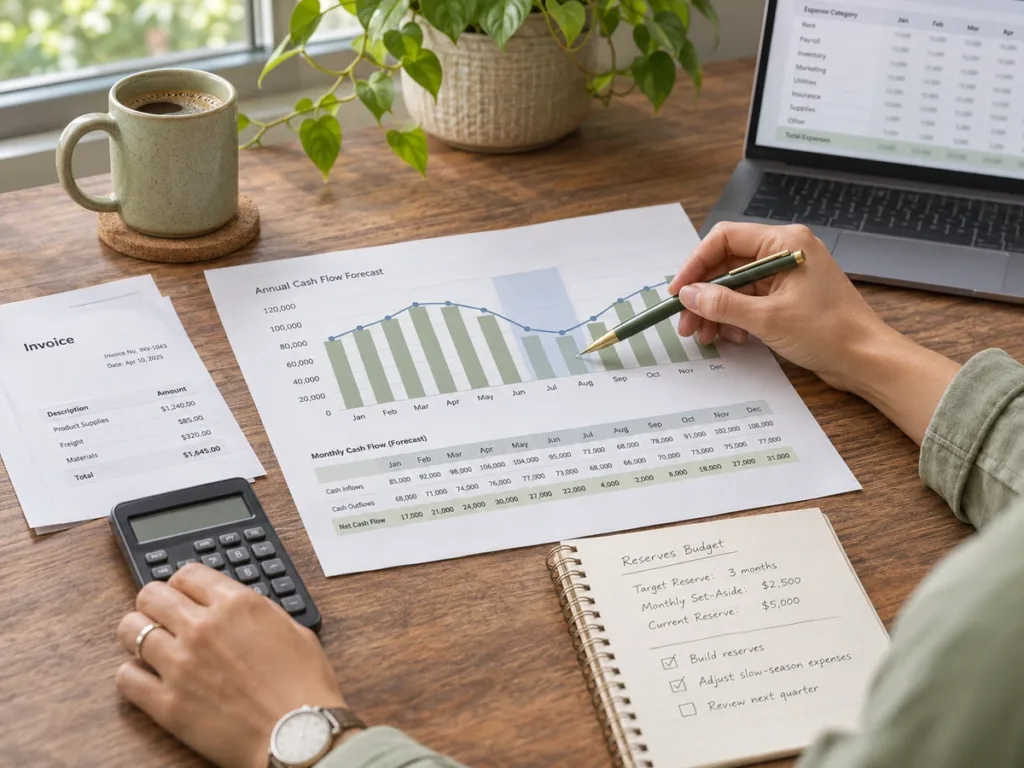
These expenses should appear in the forecast before their due dates.
Setting aside appropriate funds throughout the year can reduce the pressure created by large scheduled payments.
How Accounts Receivable Can Affect Seasonal Cash Flow
Accounts receivable represents money customers owe a business for goods or services already provided on credit.
For seasonal companies, unpaid invoices can create financial challenges when customer payments arrive after the busiest sales period.
Strong sales do not always mean strong cash flow
Imagine a contractor completes $40,000 in projects during a busy month.
If customers have not paid, the company may still struggle to cover payroll, materials, and other bills.
The business has generated revenue, but the cash has not yet been collected.
This is why invoice collection timing matters when developing seasonal forecasts.
Establish clear payment expectations
Businesses should communicate payment terms before completing work or delivering services.
Depending on the industry and customer relationship, these may involve deposits, progress payments, or payment upon completion.
Clearly documented terms can reduce misunderstandings and make collection timing more predictable.
Invoice customers promptly
Delaying invoices can delay payment.
Businesses should establish a consistent process for preparing and sending invoices once the relevant billing requirements have been met.
Accounting software may help automate recurring invoices and payment reminders.
However, businesses still need to verify invoice amounts and resolve customer disputes.
Review outstanding balances
An accounts receivable aging report can show how long customer invoices have remained unpaid.
Owners should regularly review overdue balances and determine whether additional follow-up is necessary.
For seasonal businesses, collecting outstanding payments before revenue declines can help strengthen cash availability during slower periods.
Should You Adjust Inventory or Staffing by Season?
Inventory and labor expenses often change with customer demand.
Businesses with seasonal operations may benefit from adjusting purchasing and staffing plans to reflect expected activity.
However, these decisions should account for operational requirements and customer service expectations.
Align inventory purchases with demand
Retailers and other product-based businesses may need additional inventory during busy seasons.
Purchasing too much inventory can tie up cash that might otherwise be available for operating expenses.
Businesses should review previous sales, supplier lead times, and expected customer demand before placing large orders.
They should also consider storage costs, product expiration, and the risk of unsold inventory.
Monitor inventory turnover
Inventory turnover helps businesses understand how quickly products are sold and replaced.
Slow-moving inventory may indicate that purchasing levels exceed customer demand.
Identifying excess stock before a slower season can help businesses make better purchasing decisions.
However, reducing inventory too aggressively can lead to shortages and missed sales opportunities.
Plan staffing around expected workloads
Businesses may experience predictable changes in labor needs throughout the year.
Seasonal employees, temporary staffing arrangements, or adjusted work schedules may provide flexibility.
However, staffing decisions must comply with applicable employment laws and wage requirements.
Owners should also consider training costs, employee retention, and service quality.
Prepare before demand increases
Reducing expenses during slow months is only part of seasonal planning.
Businesses must also ensure they have sufficient staff, equipment, and supplies before customer demand returns.
Planning these investments in advance can help prevent sudden cash requirements at the beginning of a busy season.
What Cash Flow Warning Signs Should You Monitor?
Seasonal revenue changes are expected for many businesses.
However, some financial trends may indicate problems beyond normal seasonal fluctuations.
Recognizing these warning signs early allows owners to investigate before available cash becomes critically limited.
Cash balances decline faster than expected
If actual cash falls significantly below forecasted amounts, determine whether the difference comes from reduced collections, unexpected spending, or inaccurate assumptions.
Repeated forecast differences may indicate that the business needs to revise its financial plan.
Overdue invoices continue increasing
A growing amount of unpaid customer invoices can create cash shortages even when sales remain strong.
Review payment terms, customer collection patterns, and outstanding balances.
Credit card balances continue growing
Using business credit cards to cover routine operating expenses may be manageable in some circumstances.
However, continuously increasing balances without a clear repayment plan can indicate that operating cash is insufficient.
Interest costs may create additional pressure during slower months.
The business delays essential payments
Difficulty paying suppliers, employees, taxes, or loan obligations on time is a significant warning sign.
Owners should investigate the cause promptly and consider appropriate professional guidance.
Busy-season profits disappear quickly
A business may experience strong sales but enter its slow season with little available cash.
This can result from high operating expenses, large inventory purchases, outstanding customer payments, or insufficient reserves.
Reviewing financial records can help determine whether the problem involves spending, collections, or the underlying business model.
How Bookkeeping Supports Better Seasonal Planning
Reliable bookkeeping provides the information businesses need to understand seasonal financial patterns.
Without organized records, owners may rely on estimates or assumptions when determining whether enough cash will be available.
Historical records reveal seasonal patterns
Accurate income and expense records allow businesses to compare financial activity across months and years.
These comparisons help identify recurring increases in revenue, predictable operating expenses, and periods when cash requirements are highest.
Reconciliation improves financial reliability
Bank and credit card reconciliations help verify that financial transactions have been recorded correctly.
Missing entries, duplicate expenses, or incorrect classifications can distort the information used for cash flow forecasts.
Regular reconciliation makes financial reports more dependable for planning purposes.
Expense categories support better decisions
Organized expense records help owners distinguish between fixed costs, variable operating expenses, and occasional purchases.
This information is useful when determining which expenses may be adjusted during seasonal slowdowns.
Financial reports provide context
Profit and loss statements, balance sheets, and cash flow reports can help business owners evaluate different aspects of their operations.
However, each report serves a different purpose.
A profit and loss statement measures income and expenses over a period, while a cash flow report focuses on movements of cash.
Understanding these differences helps prevent decisions based on incomplete information.
Bookkeeping does not eliminate seasonal uncertainty, but it provides a stronger foundation for forecasting and financial planning.
Cash Flow Support in Fort Mill
Seasonal revenue changes can affect businesses of many sizes and industries.
For business owners in Fort Mill, Tega Cay, Rock Hill, and surrounding communities, understanding financial trends is important when preparing for periods of fluctuating demand.
At Abacus Tax & Books, we understand that reliable financial information plays an important role in business planning.
Our bookkeeping, accounting, tax consulting, and QuickBooks support services help small business owners maintain organized financial records and better understand their business finances.
For companies experiencing seasonal changes in sales, maintaining accurate records can make it easier to identify historical patterns, evaluate expenses, and prepare financial projections.
We help business owners address bookkeeping concerns, review financial information, and maintain records that support informed decisions.
Whether a business experiences seasonal peaks in retail sales, changing service demand, or fluctuations in project-based revenue, organized accounting information provides valuable context.
Our goal is to help clients understand their financial position and maintain bookkeeping practices that support their operations throughout the year.
Prepare Your Business for Every Season With Abacus Tax & Books
Seasonal fluctuations do not have to leave business owners uncertain about their financial position.
With accurate records and a clear understanding of expenses, receivables, and revenue patterns, businesses can prepare more effectively for both busy and slower periods.
At Abacus Tax & Books, we help small business owners maintain organized financial information and address accounting challenges that may affect their planning.
Our bookkeeping and QuickBooks support services can help businesses improve recordkeeping consistency, review financial transactions, and better understand the numbers behind their operations.
We also provide tax consulting and preparation services to help clients address important financial and tax-related responsibilities.
Whether you are preparing for a slower season or reviewing your business’s financial performance after a busy period, our team is available to discuss your accounting needs.
Contact Abacus Tax & Books at (803) 548-1099 to schedule a consultation and learn how we can support your business’s financial recordkeeping and planning needs.
FAQs About Seasonal Cash Flow
What is seasonal cash flow?
Seasonal cash flow refers to changes in the amount of money entering and leaving a business during different times of the year. These fluctuations often result from predictable changes in customer demand, operating expenses, or payment schedules.
How can small businesses prepare for slow seasons?
Businesses can prepare by reviewing historical revenue, forecasting cash needs, building appropriate reserves, monitoring unpaid invoices, and adjusting flexible expenses. Planning should begin before the slower season arrives.
How much cash should a seasonal business keep in reserve?
There is no single reserve amount suitable for every business. The appropriate amount depends on fixed expenses, expected revenue declines, payment obligations, industry risks, and the duration of slower periods.
How often should seasonal cash flow forecasts be updated?
Monthly updates may work for businesses with predictable finances. Companies experiencing significant cash fluctuations may benefit from weekly reviews and rolling short-term forecasts.
Can a profitable seasonal business still have cash flow problems?
Yes. A business can report profits while experiencing cash shortages because of unpaid customer invoices, inventory purchases, loan payments, or expenses due before revenue is collected.
How does bookkeeping help manage seasonal cash flow?
Accurate bookkeeping helps businesses identify revenue trends, monitor expenses, track accounts receivable, and maintain reliable financial information for cash flow forecasts and seasonal planning.